

Don’t worry. You didn’t miss a press release. There was no launch event. But over the past couple of years, the online travel agency (OTA) has been steadily expanding its footprint in tours, activities, and attractions.
Booking’s history in the sector goes back more than a few years. The company had been developing its own attractions offering before the pandemic and then made a significant move in 2018 with the acquisition of FareHarbor, one of the largest booking systems in the sector.
That approach shifted in 2020, during the pandemic, when Booking stepped back from direct contracting. Instead, it moved to a partner-led model, signing deals with TUI Musement later that year, followed by Viator in 2021.
More recently, the company has been moving back into direct relationships, building connections to a limited number of booking systems and selectively contracting with tour and activity operators and attractions.
Stay First, Experience Second
Booking’s approach to experiences sits within its broader “connected trip” strategy, a concept promoted by CEO Glenn Fogel focused on bringing accommodation, transport and in-destination experiences into a more integrated itinerary and overall journey.
“Attractions are often the most meaningful part of a trip… which is why they’re deeply embedded in our strategy,” said Sam Harris, Managing Director, Attractions.
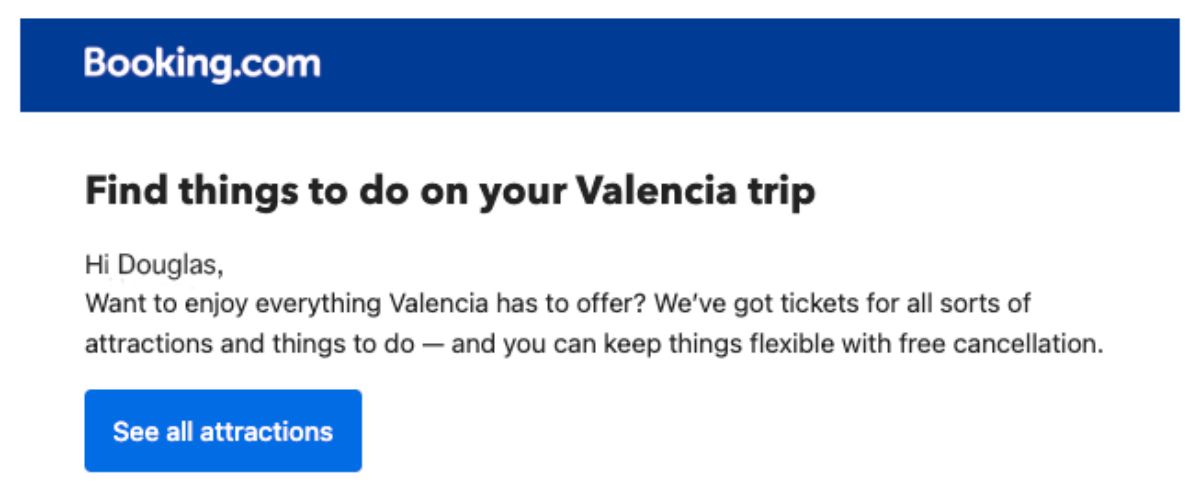
In practice, however, experiences are positioned as an “attached product,” with accommodation at the core. Rather than acting as a primary entry point, experiences are surfaced after an accommodation booking is made, typically through post-booking emails or in-app prompts, based on a traveler’s destination, dates and available inventory.
How Booking Is Building Direct Supply
For now, Booking’s supply strategy remains largely partner-led. The vast majority of its inventory — now spanning more than 3,200 cities globally — comes through OTA partners including Viator, TUI Musement and Klook, as well as the FareHarbor distribution network (an opt-in channel for operators using FareHarbor to sell their tours and tickets to connected resellers).
Booking has begun expanding its base of directly contracted experiences, but the scope remains narrow. The focus is on larger operators and major attractions in key markets, particularly across Europe and the U.S., with expansion to other regions expected to follow.
Priority is being given to high-demand, high-volume products — “iconic” or “must-see” experiences in major destinations.
“Our starting point is demand, focusing on the destinations and experiences that matter most to customers,” said Harris. “That typically means prioritizing the most sought-after attractions in key markets.”
The company is not yet set up to onboard the longer tail of small and mid-sized operators, he noted, and will continue to source that supply through its OTA partners.
13-15 April 2027 Insider Pro Access Members Save 20% THE event of the year for the European in-destination experiences industry Save up to €850 with an Autumn Advantage Ticket as an Insider Pro Member!
What Operators Need to Know
For larger operators and attractions, Booking’s model is broadly in line with other OTAs, with one key difference: API connectivity is required.
The company operates entirely through API integrations, with availability, pricing and content all managed directly through connected booking systems. There is no manual setup, and no extranet planned for operators that are not connected.
Booking currently works with a limited set of reservation and connectivity and channel management providers, including Ventrata, Palisis and PrioTicket, alongside its OTA partners. Operators using systems that support the OCTO standard may find integration easier, but API capability remains a prerequisite.
Commercial terms are broadly in line with other OTAs, though details vary by partner type. Harris declined to go into specific commission levels.
Should Operators Reach Out?
Harris said the Booking team is open to conversations with operators and will be present at industry events, including upcoming Arival events. Operators can also reach out directly .
For now, the focus remains on larger attractions and high-volume operators in key markets. Those that fit that profile — particularly in Europe and the U.S. — may find it worthwhile to engage.
Onboarding is progressing deliberately, and operators should expect a measured process as Booking continues to build out its capabilities. Smaller and mid-sized operators will continue to access the platform primarily through OTA partners.
Will Booking Succeed in Experiences?
Booking’s re-engagement with the category is significant. Its scale in accommodation — measured in gross bookings and room nights — makes it the largest online travel seller, well ahead of competitors such as Expedia and Airbnb.
But tours, activities and attractions remain a difficult sector to crack. Supply is highly fragmented, and customer expectations vary widely depending on the type of experience: how travelers plan and book a museum ticket, a guided tour or a football match can be fundamentally different. These dynamics have consistently challenged broader travel platforms entering the sector. Success in hotels does not automatically translate to success in experiences.
Attach rates — the share of accommodation bookings that convert into experience bookings — remain relatively low, the company acknowledged, and improving that conversion will take time.
In addition, there’s an important, global consumer shift underway, as more and more travelers – especially the rising cohort of Gen-Z and Millennials – are putting experiences at the forefront of their trip planning. Younger travelers are booking more tours and attractions further in advance, and Arival’s 2026 U.S. Experiences Traveler Outlook shows that more 18-34-year-old travelers say experiences are important to the decision on where to go on a trip. How Booking.com addresses this consumer trend with an accommodation-first strategy remains to be seen.
For now, Booking’s approach is additive rather than transformative. It does not materially affect most operators in the near term, but it does introduce another distribution channel, particularly for high-demand products. It is, however, an initiative the industry — operators, technology providers, and especially Booking’s competitors — should watch closely.
Learn More About Experiences, OTAs and More with Arival
Keep up with the latest on distribution, OTAs and the ever-evolving experiences industry landscape with Arival. Join us at the next Arival event to stay up to date on the latest developments in the experiences sector directly from tours, activities and attractions industry leaders and experts.
Become an Insider Pro Access member today and get access to the full library of Arival research, plus many other benefits such as free consulting sessions, special discounts and 20% off in-person events, starting from $179 per year.
Sign up to receive insights tailored for the in-destination industry as well as updates on Arival.