

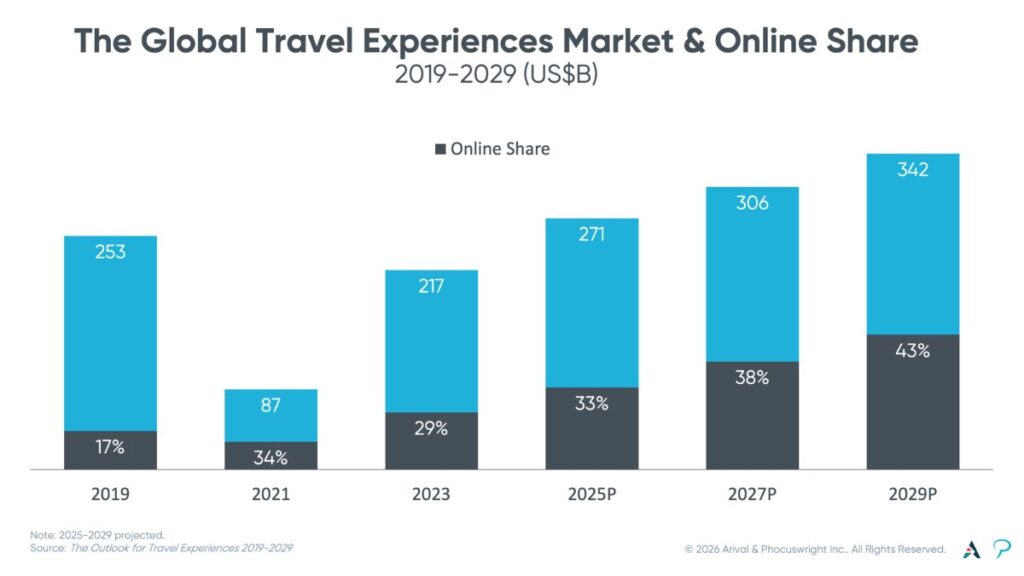
Experiences are no longer riding in the back seat of the travel economy: they are driving the bus. At $271 billion in 2025 and projected to reach $342 billion by 2029, tours, activities and attractions are now seeing growth that outpaces every other major segment of the travel industry.
That’s the headline finding from The Outlook for Travel Experiences 2019–2029, the most comprehensive global market-sizing report for our sector since before the pandemic, released by Arival and Phocuswright. The research confirms what many in the industry have long suspected — something big is happening in experiences.
Built from extensive operator data, global traveler research, third-party economic indicators and a detailed supply-side model, this report gives our industry the clearest, most authoritative picture of its own scale that we’ve had in years. Here’s a preview of what we found — and what it means for operators of tours, activities and attractions.
Experiences Have Moved to the Center of the Travel Decision
For years, tours, activities and attractions were treated as a nice-to-have — something travelers figured out once they arrived at their destination. No longer. The latest research confirms a structural shift: experiences are now a primary driver of destination choice, rather than an afterthought.
Travelers are prioritizing experiences like never before, fueled by a generational preference for “experiences over things” and a rapid shift toward planning and booking in advance.
The sector has not only recovered since the pandemic era — at a projected growth of 8% CAGR from 2023-2029, versus 5% in the wider travel sector, it is now one of the fastest-growing parts of travel, reshaping how people choose where to go and what to do.
Operator Takeaway: This is the market validation many operators have felt on the ground, but until now have not had the numbers to prove. Tour, activity and attraction products are no longer peripheral to the travel decision — they’re central to it. That has real implications for how you position your business, how you price, and how you engage with distribution partners.
13-15 April 2027 Insider Pro Access Members Save 20% THE event of the year for the European in-destination experiences industry Save up to €850 with an Autumn Advantage Ticket as an Insider Pro Member!
Online Booking Is Accelerating — But There’s Still a Significant Gap in Operators’ Digital Adoption
One of the most striking findings in the report is the pace of digital acceleration in the sector — and the gap that still remains. Online channels have grown from just 17% of bookings in 2019 to a projected 42% by 2029, with online travel agencies (OTAs) emerging as the fastest-growing channel, expected to see more than fivefold growth in gross bookings over that same period.
But here’s the thing: even with all that growth, our sector is still significantly under-digitized. In 2025, only 33% of gross bookings in experiences took place through online channels — compared to 64% for the broader global travel industry.
That gap isn’t a weakness; it’s an opportunity. As more operators adopt modern booking systems and as AI begins to reshape how travelers discover and book experiences, the online booking market is poised to expand dramatically.
Operator Takeaway: Invest in your digital infrastructure now — whether that’s upgrading your online booking (restech, or reservation technology) systems, expanding your OTA connectivity, or optimizing your tech stack — to make it easier for customers to find and book your products online, thus positioning yourself ahead of the wave that is still building momentum.
Check out these Arival resources to help guide you:
The Full Picture Is Waiting for You
The experiences sector is at an inflection point. Investor interest is surging, with major players like Klook, GetYourGuide and MyRealTrip eyeing public markets, and global platforms like Airbnb, Booking.com and Expedia aggressively expanding their experiences offerings. The momentum is real — and so are the challenges, from fragmentation and uneven tech adoption to AI-driven changes and intensified competition in the experiences marketplace.
The Outlook for Travel Experiences 2019–2029 digs into all of it: the growth projections, the channel shifts, the competitive dynamics, and what it all means for operators, platforms and investors navigating this moment. If you want the complete picture — including the regional breakdowns, supply-side analysis and forward-looking projections — download the full report today. The full report is available at no additional cost for Arival Insider Pro Access members, or for $895 to non-members.
Become an Insider Pro Access member today and get access to the full library of Arival research, plus many other benefits such as free consulting sessions, special discounts and 20% off in-person events, starting from $179 per year.
Sign up to receive insights tailored for the in-destination industry as well as updates on Arival.
Header image: Pexels / Jess Loiterton