

Travelers don’t just want to see the sights — they want to do the things. Activity operators in particular have been experiencing a boom in recent years, driven by a fundamental shift in what travelers want.
The global experiences sector is already outpacing the rest of travel, growing at 8% annually compared to 5% for the wider travel industry, according to The Outlook for Travel Experiences 2019–2029, a joint report by Arival and Phocuswright. But within that already strong picture, one segment stands out: the data confirms that activities are growing faster than any other part of experiences.
Here’s what’s behind the boom, and what experience operators of all types can do to attract increasingly activity-oriented travelers.
Activities Are Taking the Lead
The numbers from the latest Arival and Phocuswright research tell a clear story. The activities segment — which includes outdoor adventure, wellness, cultural classes, water-based experiences and more — is projected to reach $127 billion by 2029, growing at 7-8% annually, outpacing both tours and attractions.
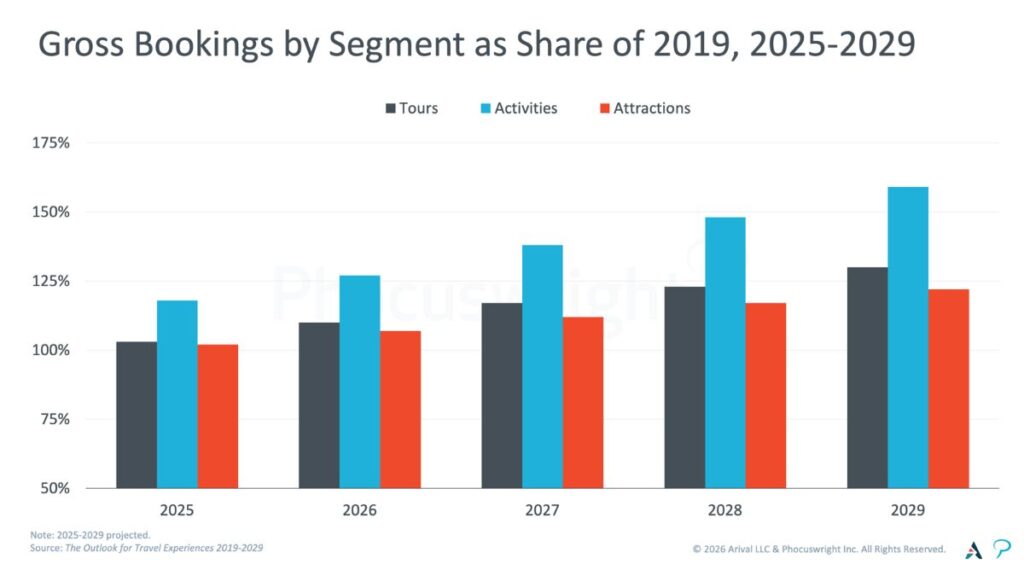
The activities segment has been on a remarkable run. It was the quickest part of the experiences sector to rebound after the pandemic — surging from $21 billion in 2020 to $95 billion by 2025 — and has continued to accelerate since.
The result is a meaningful shift in market share: activities will account for 37% of the global travel experiences market by 2029, up from around 32% in 2023.
13-15 April 2027 Insider Pro Access Members Save 20% THE event of the year for the European in-destination experiences industry Save up to €850 with an Autumn Advantage Ticket as an Insider Pro Member!
What’s Driving It?
The activities surge is not a trend in the traditional sense — it is the result of a deep, structural shift in consumer behavior that was already underway before the pandemic, and accelerated sharply coming out of it.
When travel resumed, activities led the recovery, as travelers who had spent years unable to get outside, try new things and connect with the world around them came back with a renewed sense of purpose — and a clear preference for active, participatory experiences over passive ones. Outdoor adventure, wellness, hands-on cultural immersion: these were the categories that bounced back fastest, and that momentum has carried forward.
This aligns with what Arival’s own consumer research has found consistently: experiences are now one of the most important factors in destination selection. And it’s not just that travelers are choosing more experiences: they’re spending more on them. Experiences — particularly the more immersive ones — attract a growing wave of affluent travelers willing to pay more for private and premium products.
In essence, the traveler who books a kayaking excursion, a cooking class or a sunrise yoga session is not just any traveler — they’re often a high-value customer who plans ahead, seeks out meaningful things to do, and is likely to share their experience afterward.
What This Means for Operators
The activities boom carries implications that go well beyond activity operators themselves.
If you operate activities: The demand is there and growing. The opportunity now lies in capturing it more effectively — through stronger digital presence, better OTA listings and smarter pricing. The report highlights that dynamic pricing adoption is still low across the sector despite being one of the clearest levers for revenue growth. Activity operators who get ahead of this trend will be better positioned to maximize revenue as demand continues to rise.
If you operate tours: The shift toward active, participatory experiences is a signal worth heeding. Operators who find ways to incorporate more hands-on, immersive or active elements into their products — rather than relying solely on narration and sightseeing — will be better aligned with where traveler preferences are heading.
If you operate an attraction: The fastest-growing attractions are those adding experiential, guided and interactive layers to their offering. Static visits are losing ground to dynamic, participatory experiences. The data supports investment in guided tours, VIP experiences and interactive programming as ways to drive both revenue and satisfaction.
Get the Full Picture
The activities surge is one of several major findings in The Outlook for Travel Experiences 2019–2029. The full report covers regional growth projections, channel shifts, the OTA competitive landscape, pricing trends and more — giving operators and other industry leaders the data and context to make smarter decisions about where to invest and how to grow.
The full report is available at no additional cost for Arival Insider Pro Access members, or for $895 to non-members.
Hear more about the trends shaping the future of experiences in person at upcoming Arival events in Valencia, Brisbane and Spokane.
Become an Insider Pro Access member today and get access to the full library of Arival research, plus many other benefits such as free consulting sessions, special discounts and 20% off in-person events, starting from $179 per year.
Header photo: Pexels / Karson